Peloton Interactive(NASDAQ: PTON) makes stationary train bikes, treadmills, and rowing machines, which it primarily sells to customers for at-home use. Its inventory went public in September 2019 priced at $29, however by the top of 2020, it had soared to a peak of $163. The COVID-19 pandemic sparked a surge in demand for the corporate’s gear, as lockdowns and social restrictions restricted the usage of gyms and different coaching amenities.
However when social circumstances began to normalize in 2022, demand for Peloton’s {hardware} plummeted. The corporate was confronted with shrinking income and rising losses, which at one level threatened its very survival.
Will AI create the world’s first trillionaire? Our workforce simply launched a report on the one little-known firm, referred to as an “Indispensable Monopoly” offering the important know-how Nvidia and Intel each want. Continue »
Peloton continues to wrestle with weak gross sales, however the firm’s backside line is now in a lot better form due to a collection of drastic price cuts. With its inventory buying and selling 96% under its 2020 excessive, may this be a very good time for buyers to purchase?
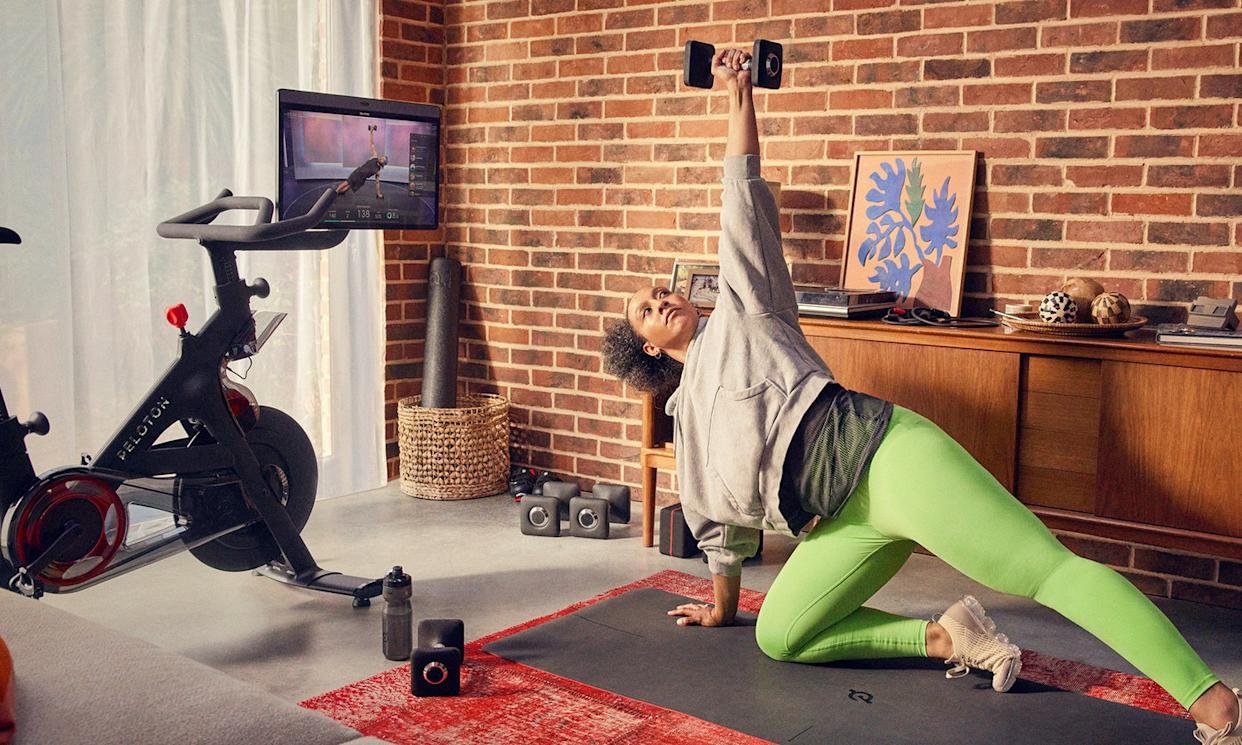
Picture supply: Peloton Interactive.
This is the unhealthy information
Peloton’s enterprise has undergone a big transformation over the previous couple of years. In fiscal 2021 (ended June 30, 2021), train gear gross sales had been the biggest contributor to the corporate’s $4 billion in whole revenue. However by means of the primary three quarters of fiscal 2026 (ended March 31), gear gross sales represented lower than one-third of its income base.
That is principally as a result of demand for Peloton’s merchandise collapsed after the height of the pandemic, but it surely additionally displays a shift towards digital subscription companies. The corporate affords a related health subscription for purchasers who personal its train gear, which provides them entry to digital courses and real-time efficiency monitoring. The corporate additionally affords a separate subscription to its cell app for purchasers who do not personal its gear, which supplies them with exercise plans and different primary options.
These subscriptions now account for the majority of Peloton’s income. On the plus facet, they’ve excessive revenue margins, however they are not very sticky, so it is powerful to maintain members round. The truth is, in the course of the third quarter, Peloton’s related health subscriber base shrank 8% yr over yr to 2.66 million members, and its paid app subscriber base declined by 9% to 522,000 members.
In different phrases, not solely is Peloton struggling to promote gear, but it surely’s additionally having bother sustaining its membership base.
Consequently, the corporate’s whole income has declined in each single yr since fiscal 2021, and it is on observe to say no once more throughout fiscal 2026, in response to administration’s steering.
Fiscal 12 months
Income
Income Progress (Contraction)
Fiscal 2021
$4.02 billion
120%
Fiscal 2022
$3.58 billion
(11%)
Fiscal 2023
$2.8 billion
(22%)
Fiscal 2024
$2.7 billion
(4%)
Fiscal 2025
$2.49 billion
(7%)
Fiscal 2026 (forecast)
$2.43 billion
(2%)
Knowledge supply: Peloton Interactive.
On to the excellent news
Peloton’s administration workforce gave the impression to be caught off guard when income began shrinking in fiscal 2022, as a result of that they had positioned the corporate’s prices as if extra progress was coming. Due to this fact, with much less cash coming in and extra money going out, Peloton suffered a staggering internet lack of $2.8 billion that yr. If administration did not act quick to slash prices, the corporate in all probability would not have survived.
Peloton is now spending much less on every thing from advertising and marketing to analysis and improvement. Through the first 9 months of fiscal 2026, the corporate’s whole working bills had been simply $862 million — down sharply from $2.2 billion within the first 9 months of fiscal 2022. Consequently, it has eked out a small usually accepted accounting ideas (GAAP) revenue of $1.6 million in fiscal 2026 to this point, so chapter is not an actual danger within the close to time period.
However there’s a catch. By consistently slicing prices, Peloton is investing much less in creating new merchandise and buying new clients, making it more durable to generate income progress. The corporate will ultimately run out of how to cut back bills, so if it does not discover a approach to generate an natural enhance in gear and subscription gross sales, it’s going to inevitably begin making losses once more.
Is it time to purchase Peloton inventory?
Peloton is making an attempt to spice up gross sales in just a few alternative ways. It now sells gear by means of third-party retailers like Amazon, Dick’s Sporting Itemsand even Costco. And in the course of the current third quarter, it launched business variations of its flagship treadmill and train bike to promote to gyms and different coaching amenities. The shift into business-to-business gross sales will definitely increase the corporate’s addressable market.
Peloton has $1.1 billion in money available, so it has some headroom to experiment with completely different methods, particularly now that it is producing GAAP earnings. However the firm can also be carrying $944 million in long-term debt, so it has a really restricted window of alternative to supply outcomes.
Wall Avenue is not satisfied gross sales progress is on the horizon as a result of analysts are forecasting flat income in fiscal 2027. Peloton has already had 5 years to show it could flip its dwindling gross sales round with out success, so it in all probability is not sensible for buyers to wager on a distinct end result proper now.
A beaten-down inventory is not at all times an affordable inventory, so I do not assume Peloton’s 96% decline represents a shopping for alternative.
Must you purchase inventory in Peloton Interactive proper now?
Before you purchase inventory in Peloton Interactive, think about this:
The Motley Idiot Inventory Advisor analyst workforce simply recognized what they imagine are the 10 best stocks for buyers to purchase now… and Peloton Interactive wasn’t considered one of them. The ten shares that made the reduce may produce monster returns within the coming years.
Take into account when Netflix made this record on December 17, 2004… should you invested $1,000 on the time of our advice, you’d have $469,293!* Or when Nvidia made this record on April 15, 2005… should you invested $1,000 on the time of our advice, you’d have $1,381,332!*
Now, it’s price noting Inventory Advisor’s whole common return is 993% — a market-crushing outperformance in comparison with 207% for the S&P 500. Do not miss the newest high 10 record, accessible with Inventory Advisorand be a part of an investing group constructed by particular person buyers for particular person buyers.
Anthony Di Pizio has no place in any of the shares talked about. The Motley Idiot has positions in and recommends Amazon, Costco Wholesale, and Peloton Interactive. The Motley Idiot has a disclosure policy.