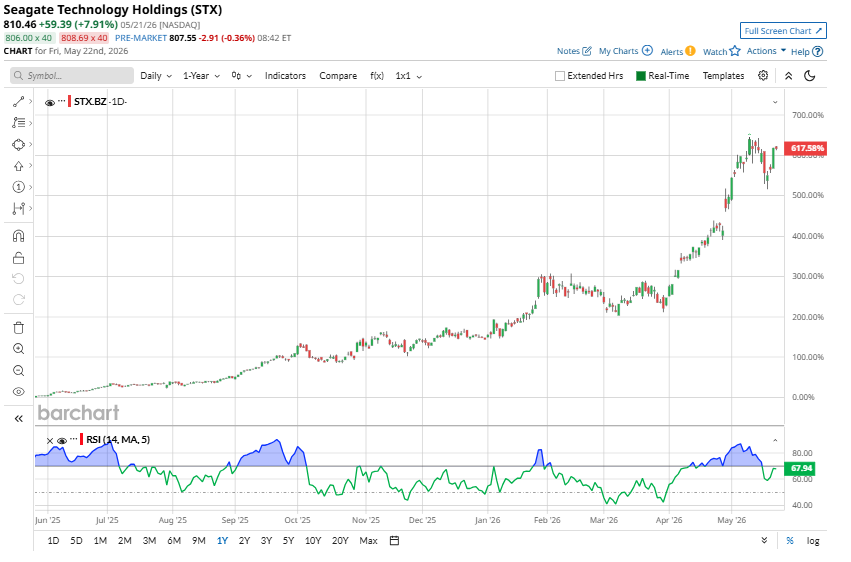
Seagate Know-how (STX) has been one of many best-performing shares within the S&P 500 Index ($SPX) this yr, with shares hovering 195.42% year-to-date (YTD). The inventory’s stellar rally locations it among the many market’s prime gainers, behind solely Sandisk (SNDK) and Intel (INTC), whose shares have climbed roughly 529.26% and 224.15%, respectively, over the identical interval.
The surge in Seagate’s inventory has been pushed by rising demand for high-capacity knowledge storage options as firms ramp up spending on synthetic intelligence (AI) infrastructure. The fast growth of AI functions is creating an infinite want for knowledge facilities able to storing and processing large quantities of data, and Seagate is benefiting from this pattern.
Extra Information from Barchart
On the identical time, favorable trade dynamics are strengthening the corporate’s monetary efficiency. Restricted provide throughout the storage market has helped enhance pricing situations, permitting Seagate to generate stronger income and better profitability. These enhancing fundamentals have performed a serious position in driving investor confidence and supporting the inventory’s sharp rise.
Even after its spectacular beneficial properties, listed here are three the explanation why Seagate inventory may nonetheless hold rallying.
The rally in STX seems sustainable, supported by robust demand for high-performance storage options and favorable pricing.
In its newest quarter, Seagate Know-how reported $3.1 billion in income, pushed primarily by its knowledge middle enterprise, which accounted for almost 80% of gross sales and grew 55% year-over-year (YOY). Progress displays rising demand from hyperscale cloud and enterprise prospects in search of scalable, cost-efficient storage infrastructure.
Profitability improved sharply as adjusted gross revenue reached $1.5 billion, whereas gross margin expanded to 47% from 42.2% within the prior quarter. Higher pricing and an improved mixture of high-capacity merchandise supported the margin beneficial properties.
Lengthy-term, AI adoption is accelerating knowledge creation and rising the necessity for long-term storage and historic knowledge evaluation. Demand is increasing past conventional cloud environments into enterprise edge deployments, reflecting the rising want for high-capacity onerous drives in trendy knowledge facilities.
And, Seagate is strengthening its place by way of its Mozaic platform and Warmth-Assisted Magnetic Recording (HAMR) know-how, which goals to extend storage density and effectivity. These improvements may assist future demand and margin growth.
Moreover, the corporate’s build-to-order (BTO) manufacturing mannequin improves visibility into buyer demand whereas supporting pricing and provide stability.
General, rising storage demand, enhancing pricing traits, and Seagate’s operational self-discipline place the corporate for continued income and earnings progress, supporting additional upside in its inventory worth.
Purpose #2: Seagate’s Steadiness Sheet Is Enhancing Quick
Seagate Know-how’s disciplined capital allocation technique is concentrated on decreasing debt and strengthening its stability sheet, supporting long-term progress and shareholder returns. Over the last reported quarter, the corporate repaid $641 million in debt, decreasing gross debt to about $3.9 billion. Because the begin of fiscal 2026, Seagate has decreased whole debt by roughly $1.1 billion, reflecting constant monetary self-discipline and give attention to decreasing stability sheet danger.
The corporate’s leverage profile has improved considerably, with internet leverage declining to 0.7 instances within the March quarter, backed by adjusted EBITDA of $1.2 billion. Decrease leverage enhances Seagate’s monetary flexibility and talent to take a position for future progress whereas managing obligations successfully.
With enhancing profitability and robust money technology, Seagate seems well-positioned to proceed lowering debt within the coming quarters, additional strengthening its monetary basis and general stability.
Regardless of Seagate’s robust inventory efficiency, its valuation nonetheless seems to be interesting relative to its earnings progress potential.
The information storage large continues to profit from sustained demand for high-capacity storage options, pushed by the fast growth of AI knowledge facilities, cloud computing, and enterprise knowledge wants. On the identical time, Seagate’s ahead price-to-earnings ratio of 53.27 instances seems affordable given the corporate’s anticipated earnings progress trajectory. Analysts forecast Seagate’s earnings-per-share to surge by 81% to $25.52 in fiscal 2027, indicating the potential for continued momentum within the inventory. With robust trade tailwinds and accelerating profitability, Seagate nonetheless presents significant upside for long-term buyers.
Closing Takeaway
Seagate’s large run in 2026 is supported by structural demand, enhancing pricing situations, and quickly increasing profitability. With storage demand persevering with to surge and monetary fundamentals strengthening, Seagate’s rally should still have additional to go. Analysts are bullish and keep a “Sturdy Purchase” consensus ranking.
www.barchart.com
www.barchart.com
On the date of publication, Amit Singh didn’t have (both instantly or not directly) positions in any of the securities talked about on this article. All data and knowledge on this article is solely for informational functions. This text was initially printed on Barchart.com